
Ghana’s renewed push to expand domestic petroleum refining is increasingly becoming a question of how the country manages risk across its entire downstream system, rather than simply how much refining capacity it can build.
The reopening of the Tema Oil Refinery (TOR), plans to expand its capacity, rising output from private refining facilities and efforts to channel Ghanaian crude into domestic processing are all unfolding against a more difficult international fuel market.
That makes the refining debate more consequential.
For Ghana, the objective is not necessarily to eliminate imports altogether. It is to create enough domestic processing capacity, commercial flexibility and supply options to prevent an external disruption from quickly becoming a domestic energy crisis.
An energy expert who spoke exclusively to The Vaultz News previously argued that Ghana’s refining strategy should not be reduced to the question of whether state ownership or private ownership is the superior model.
The more important test, the expert said, is whether the facilities can operate commercially, receive reliable crude, compete fairly and function within predictable regulatory conditions.
“Commercially driven operations, transparent regulation, reliable crude supply and predictable market policies are more important than whether a refinery is privately or publicly owned.” Energy Expert, speaking exclusively in an interview.
Refining Becomes Energy-Security Infrastructure
Ghana’s exposure to international petroleum markets has made local refining increasingly important to the country’s energy-security calculations.
A functioning domestic refinery does not automatically insulate Ghana from global oil prices. Crude still has to be sourced, refiners still face and operating costs and petroleum products remain connected to international market conditions. But domestic processing can change the nature of the vulnerability.
Instead of relying almost entirely on imported finished products, Ghana can create an additional layer of flexibility by processing crude locally and maintaining greater control over part of the supply chain.
That distinction has become more important as international petroleum markets face renewed supply uncertainty.
Ghana’s own downstream market has recently demonstrated the difference between fuel availability and fuel affordability. The National Petroleum Authority has maintained that the country has sufficient stocks to cover near-term demand, while acknowledging that international conditions remain a major threat to prices.
The implication is straightforward: having fuel in storage does not mean Ghana has escaped the international market.
Domestic refining therefore matters not simply because it produces fuel, but because it can potentially reduce the country’s dependence on imported refined products.
TOR’s Revival Must Become Commercially Sustainable
This is where TOR’s revival assumes strategic significance.
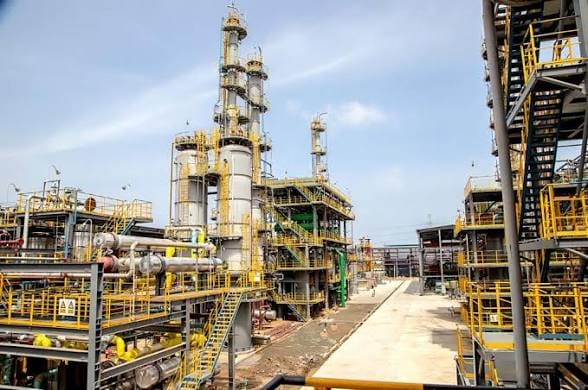
The refinery’s return to operation following the refurbishment of its Crude Distillation Unit has created renewed expectations that the state-owned facility can become part of Ghana’s response to downstream supply vulnerability. Parliament’s Energy Committee has also been monitoring TOR’s operations and revival plans as part of its oversight responsibilities.
Tema Oil Refinery
Yet the difficult question begins after rehabilitation.
A refinery can be restored technically and still struggle commercially.
The expert’s assessment points directly to that distinction. Ghana does not necessarily need to choose between a public refinery and private refineries. It needs an operating environment in which each facility can survive on the strength of its economics while contributing to national supply security.
That means crude must arrive consistently. Financing must be available. Maintenance cannot be deferred indefinitely. Product offtake must be predictable. Pricing must allow refiners to recover their costs without creating distortions that ultimately return to the public purse.
In that sense, TOR’s revival is only the beginning.
The real measure of success will be whether the refinery can move from being an emergency national asset to being a commercially disciplined participant in the petroleum market.
Local Crude Could Change The Equation
One of the most important developments in Ghana’s refining strategy is the effort to connect domestic crude production more directly with domestic processing.
That approach addresses two problems simultaneously.
Ghana produces crude but has historically relied heavily on imported refined petroleum products. Connecting local crude to domestic refineries creates an opportunity to retain more value within the country and reduce the mismatch between upstream production and downstream consumption.
The expert previously warned that Ghana should establish clear commercial rules around domestic crude allocation before tensions emerge between export interests and the requirements of local refineries.
“A predictable commercial arrangement between upstream producers and domestic refiners is essential.” Energy Expert.
That principle becomes particularly important as Ghana seeks to increase refinery utilisation.
If domestic crude is supplied inconsistently, refiners may be forced back onto imported feedstock. The country could then end up owning refining capacity without materially reducing its exposure to international supply conditions.
The challenge, therefore, is not simply to reserve crude for local refining. It is to establish a transparent framework that makes the arrangement commercially viable for both upstream producers and domestic refiners.
Dangote Should Not Define Ghana’s Strategy
Nigeria’s Dangote Refinery inevitably forms part of the regional conversation.
Its scale gives it an advantage that Ghanaian facilities cannot realistically replicate in the immediate term. But the expert’s analysis suggests that Ghana does not need to reproduce the Nigerian model to gain from a stronger refining sector.
Smaller refineries such as TOR can remain competitive by focusing on niche markets, supplying domestic demand, producing specialised petroleum products, maintaining strategic reserves and serving nearby regional markets where logistics provide a competitive advantage.”
Energy Expert.
That offers a different way of looking at competition in West Africa.
Rather than asking whether TOR can match the scale of a mega-refinery, Ghana could focus on where its own infrastructure creates an advantage.
Tema’s port, storage facilities, financial-services ecosystem and access to regional markets provide a basis for developing a downstream hub that combines refining, storage, trading and distribution.
That could prove more commercially realistic than pursuing scale for its own sake.
Crisis Exposes The Cost Of Fragmentation
The current energy environment makes this approach particularly relevant.
Ghana’s downstream petroleum security is affected by several interconnected factors: global product prices, exchange-rate movements, shipping conditions, refinery availability, storage capacity and the financial strength of companies operating across the value chain.
A weakness in one part can quickly place pressure on another.
Recent decisions around regional fuel exports have already demonstrated how domestic and regional supply priorities can intersect. Ghana’s position as a supply point for landlocked neighbours means that maintaining domestic security while remaining commercially active in regional markets requires careful management.
This is why refining cannot be treated as an isolated industrial project.
If Ghana increases refining capacity but fails to strengthen crude supply arrangements, storage, pipelines, financing and product distribution, the country may simply shift the location of its vulnerability.
The refinery may be local, but the system around it could remain fragile.
More Capacity Will Not Automatically Mean Security
Ghana’s refining ambitions are substantial. Government has indicated that expansion at TOR and Sentuo could eventually allow the two facilities to meet a significant share of domestic refined-product demand.
That would represent a major shift from Ghana’s traditional dependence on imported finished products.
But capacity figures alone should not become the measure of success.
The more relevant question is how much of that capacity can be operated consistently and economically.
A refinery that runs intermittently because of crude shortages, financing constraints, maintenance problems or weak offtake arrangements cannot provide the same security as a smaller facility that operates reliably.
This is where governance becomes more important than ownership.
Ghana Needs An Integrated Refining Market
The emerging opportunity is therefore to develop a refining system in which TOR and private refineries are not treated as competing political projects but as components of one national petroleum market.
TOR can provide strategic capacity and potentially support national reserves.
Private refineries can bring capital, operational discipline and additional processing capacity.
Upstream producers can supply crude under transparent commercial arrangements.
Storage and logistics operators can provide the infrastructure required to move products efficiently.
Government’s role should increasingly be to create the rules under which those participants can operate, rather than repeatedly stepping in to rescue individual businesses when commercial arrangements fail.
The expert’s earlier conclusion is relevant here: a hybrid structure combining private-sector efficiency with strategic government support may provide a more durable model than an ownership-based approach.
For Ghana, that means strategic state involvement does not have to translate into permanent operational control.
The Real Test Is Resilience
The refining push should ultimately be judged against one question: does it make Ghana better able to withstand the next supply shock?
If the answer is yes, then increased domestic refining can become an important pillar of energy security.
But resilience will depend on more than TOR’s revival or the construction of additional refining capacity.
It will depend on whether Ghana can secure crude, maintain commercially viable refineries, protect competition, expand storage and logistics, and create predictable rules for investors.
The country does not need to become West Africa’s largest refining power to achieve that.
It needs a petroleum system capable of continuing to supply consumers when international markets become hostile, while allowing refiners and other downstream businesses to remain financially sustainable.
That is the harder task, and ultimately the more important one.
Ghana’s refining opportunity, therefore, is not really about choosing state versus private ownership. It is about building a system in which ownership matters less than performance, commercial discipline and resilience.
And as external shocks continue to test the country’s fuel market, that distinction could determine whether the current refining revival becomes a lasting transformation or another cycle of investment followed by underutilised assets.
Leave a Reply